The Pyramid and the Exits
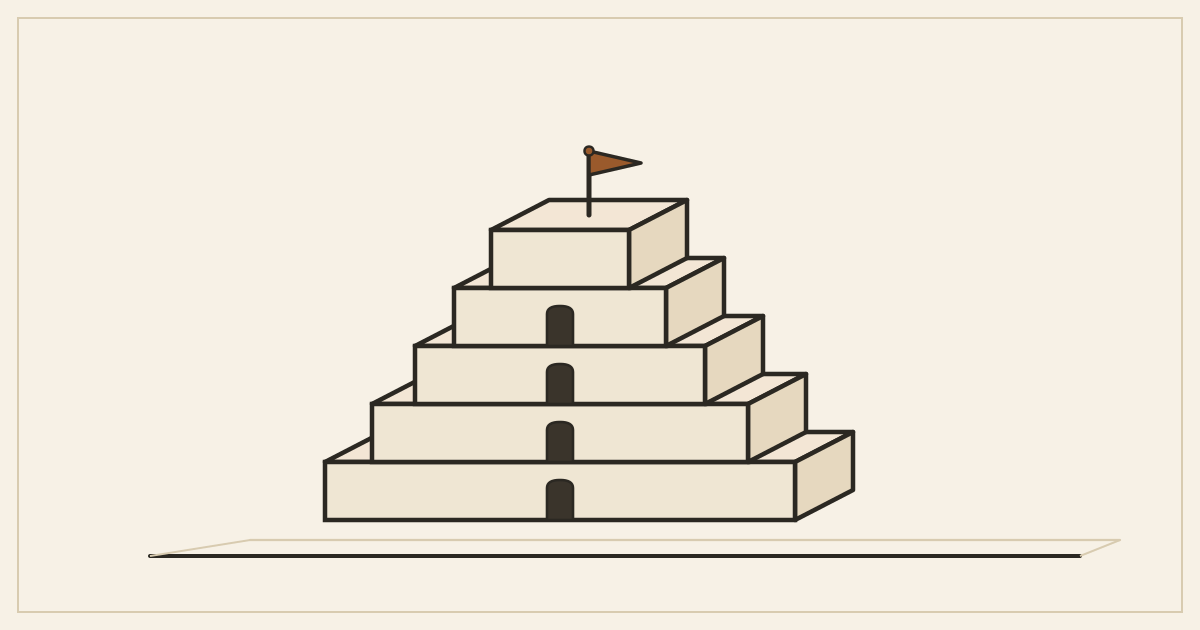
Give me thirty seconds of someone talking about markets and I can usually tell you how far up the mountain they are.
I’ve been at this almost thirty years, and in that time a great many people have shown me their strategy — or the total absence of one. The longer you do it, the less you need to place a person: the mark stays a mark in every sentence he speaks; the half-educated run on thoughts borrowed from someone else; the professionals mostly just do the thing, and say little.
What follows is my attempt to draw the main types nearly every investor falls into, the mistake that defines each one, and the single exit that leads upward. Every such scheme is arbitrary and personal. Take it as a mirror — or as a reason to dislike the author.
At the base of the pyramid stand the careless.
Let me stop on that word for a second, because it sounds like a slur, and I don’t mean it as one. I have no interest in calling anyone careless as a human being, and I’m actively annoyed by the way every profession expects its own subject to be treated as sacred. Everyone is careless about a hundred things — me included — and, on a good day, careful about a few. There’s no law that says the thing you’re careful about has to be investing. The problem isn’t being careless here. The problem is being careless everywhere, or being proud of it in some particular place (the way a certain kind of literary type loves to boast about how hopeless they are at maths).
With that out of the way: the careless investor has essentially no idea how any of this works, and not the faintest urge to change that. Rather than read two or three books and poke around online for an afternoon, they go to forums and ask questions like:
- Which government bond should I buy?
- Which fund should I pick?
- Where’s the exchange rate headed?
- I’ve got a lump of cash — what do I do with it?
Beyond the fact that zero knowledge gets you nowhere in any field, the deeper trouble is that they’re trying to handle a genuinely complex world at roughly the level of buying a washing machine. The results match. These are the people who sell in the panics and buy in the euphoria, who fall for impossible yield promises. They are the financial industry’s daily bread: responsive to marketing, blind to costs, obedient to whatever the person behind the bank desk suggests.
There’s exactly one way out of this particular hell: they cross paths with someone they find credible, who talks them into a genuinely sensible, inflation-protected holding — an inflation-linked government savings bond, say — and from then on they manage to just leave it alone.
The next group are the wanderers. Call them beginners if it’s kinder, but remember that only a sliver of beginners ever become anything more; most of the crowd here simply can’t get from one to two.
The wanderers, at least, want to learn. They’ll even read a few books, though books are dry and people much prefer to learn while being entertained. They forget one thing: a cinema ticket costs money. Entertainment has a price, and in investing that price can climb frighteningly high.
So what do they actually do? They follow whoever is loud on social media. And how do they choose whom to follow? By stage presence. By web design — I have literally met someone who trusted a source because its website looked nicer. By entertainment value. I once asked a moderately popular video host why he kept parading a monstrosity he called a portfolio, half of it a single stock. “I’m just entertaining people,” he said, “and the viewers know that.” Sure. It’ll be a barrel of laughs when they’re down 50% on it.
The point is they don’t pick their models by how useful the knowledge is — and I can’t blame them much, because that kind of content is genuinely hard to find. Ninety-nine percent of retail finance media, once it’s taught you what a share is and what a brokerage account looks like, is useless: random riffing, sometimes laced with real disinformation. The honest corners exist, but the sad truth is that serious learning means switching to English and running at least as far as the sharper end of financial Twitter for anything current, and to books for anything less time-sensitive.
I started my own market career by ordering twenty or thirty books in a few rounds and reading every one. After that it got much easier to tell who was talking pure nonsense, who was lost in some abstract theoretical fog, and who was actually trying to hand me decades of hard experience.
You can wander for a very long time. I know people who’ve been avid consumers of financial content for years, decades, without ever owning a working strategy. They’re stuck on the porch of the thing, and usually only a nasty, unexpected loss shakes them off it. Two other roads lead out. Some simply lose interest — it never rewards them, yet it demands attention, and that’s a bad trade — so they buy something simple, a fund, a bond, and abandon it to its fate. And some wake up, through a good book or plain self-reflection, to the thought that what I’ve been doing isn’t working. That thought is usually the ticket to the next level.
Now we enter the cautious builders — and anyone who’s read me before can guess this is the group I know most intimately, because they’re the ones who write after the books. They tend to have a well-paying job and a wish to set aside the income from it in some durable way. They’ve realized this takes a deliberate approach and some study, but they don’t have much time. Behind that realization there’s usually a handful of bad investments they’re now willing to admit to themselves — which is the important part. They also tend to have a low tolerance for risk, and, happily, that lines up with their actual goal: they don’t want to get rich from trading, they want to get rich from their profession.
These people usually end up at a static portfolio, occasionally seasoned with a single stock or two. But the road there is bumpier than they expect, and the most common pothole is procrastination. I know what I ought to do, and I’m not doing it. The root is usually what’s called information paralysis: too much information brings on a kind of freeze. Which index, then? What bond maturity? Gold or no gold? Which ETF? All at once or in tranches? Isn’t the market a bit rich right now?
You can smother even the simplest static portfolio under a thousand questions like these. And while you hunt for the answers, you quietly make one decision without noticing it: you don’t invest the money. That is the worst decision of the lot. Almost anything beats it — as long as you’re not taking wild risk, which this crowd never is. Build a starting portfolio in any reasonable allocation, with any decent ETFs, and then start agonizing over the details. Which, in any case, matter far less than you think.
That one pothole aside, the cautious builders are on an excellent road. Asset-allocation strategies are close to the optimal answer for an investor of average knowledge. You just have to stick with them for ten, twenty, thirty years. From this group there is no exit — or rather, the only exit leads down. Stay put.
If only it weren’t for the adrenaline. Our next crowd are the adventurers, and here is their verdict on the sensible allocation strategy I recommend to everyone: boring. And they’re absolutely right. That is one of its great virtues.
Sadly, boring doesn’t fit every personality. Sink or swim, some people need to thrash. The adventurers are well informed — they’ve read the books, they’ve got every basic and intermediate fact about stocks and bonds at their fingertips. They probably understand asset allocation perfectly well; they just don’t like it. They want dividend stocks, and property bought at the right moment, and bonds at juicy yields, and a punt on currencies. The bolder ones reach for leverage; the suicidal ones try the options market.
What moves them is adrenaline, or an excess of confidence. Medium-to-high risk tolerance, aiming for above-average returns — as a side gig. That “side gig” is exactly what separates them from the next group, and, not coincidentally, from any real chance of success. Markets, for the vast majority of the time, price financial assets efficiently, and that pricing is done around the clock by professionals all over the planet. They are the ones setting the level of the S&P 500, the exchange rate of your currency, even part of the price of local property. Do you seriously believe you’ll find the fleeting mispricings in half an hour a day, on the side?
The founding premise is simply wrong: that you can succeed as a side hobby in the sharpest competitive arena on earth.
In this group only one thing ever imposes order: dumb luck. One of them bought bitcoin early and, as it happens, sold in time, because they wanted a house. Another came into money right at the property market’s low. A third won’t be so lucky, nor the fourth, and so on down the line. The winning streaks can run astonishingly long. The very same bad decision — putting your whole account into Tesla options — can end in a fabulous profit or an enormous crater, and the thin line between the two is drawn by blind chance. By the law of large numbers the adventurers arrive at the same destination as the careless and the stuck wanderers: below-average returns. The route just has a lot more excitement in it.
Their exit, too, is handed to them by the market: a big enough loss, or, failing that, the slow loss of interest. The adrenaline won’t let them settle into a quieter tier below, and the way up is closed, because the way up requires a decision they haven’t made.
That decision is a career decision. You leave the profession you had and choose to show up on the market as a professional. The motive behind it hardly matters — you want to make a lot of money, or work from a laptop under a palm tree, or force the British pound to its knees. What matters is that you now regard the market as a craft, and as an empire waiting to be explored. That decision is the entry ticket to the young titans, at the very top of the pyramid, where the goal is durable, above-average returns.
It does not mean quitting your job tomorrow and shoving in everything you own. The decision is simply what makes the right path appear in front of you: years of apprenticeship, the accumulation of real practice, learning to sit with risk and failure. A firm career decision is what supplies the motivation and the sheer stubbornness without which you’ll get nowhere here. And building the foundation guarantees nothing. At the summit the true success rate is somewhere around one in a hundred, maybe one in a thousand — which is precisely what the young titans find attractive. To succeed where almost nobody does.
So what happens after the great decision? The titan dives in. Reads books, takes courses, hunts for mentors. Builds a strategy, backtests it, trades it. Then reads again, takes more courses, and on it goes. Systematically widens the knowledge, chews through the failures, gets up off the floor after the bigger falls. And the market selects. It throws out the weak — with one large loss, or with years of going nowhere. Nobody keeps pouring intense work, money, and energy into a thing they aren’t succeeding at. The market shoves that fact in your face, year by year, month by month, day by day. The unrelenting feedback is one of the most unpleasant features of the whole trade. Every single decision is revealed, in time, as good or bad. For a while, especially early, you can excuse yourself — the conditions are terrible, the other investors are irrational — but at the end of the day only the balance on the account has a vote.
Very few people can carry that pressure. Why do most of them ultimately fail? I doubt anyone knows the exact answer, myself included. My own passage through this was fairly smooth — profitable from the first year, though “smooth” should carry an asterisk, since in 2008 I very nearly burned the whole account to the ground. So mostly I’m leaning on what I saw when others came to me for help.
Most young titans badly underestimate the determination and the raw quantity of work success demands. Let’s grab a coffee and you can explain how this whole thing works. That’s how the majority of the approaches begin and end. Why don’t I write a book on active trading? Of course — have you read the thousand that already exist? Er, recommend a few. Amazon. Not very friendly? This world isn’t. You want knowledge that few people have. Why on earth would anyone hand it to you on a plate?
I run into risk problems constantly, too — and, oddly, at both extremes. Some refuse to take any risk they can feel. These are the paper traders: flawless in theory, but when the moment comes to press the button, it doesn’t happen. High returns, unfortunately, only come with high risk. There is no such thing as making 100% a year while never risking a 50% drawdown at some point — and 50% is a fairly good number.
The successful traders are, in a sense, functional psychopaths. Andrew Lo and Brett Steenbarger once wired up a group of day-traders and watched their bodies while they worked; a clear link showed up between the size of the nervous reaction to a loss and the shape of the profit curve. The same-sized loss simply set off a smaller physiological storm in the better traders. I don’t know how much of that is trainable and how much you’re born with, but I do know that above-average returns require above-average appetite for risk.
The other extreme is the people who take risk with no sense at all. It’s worthless to generate a huge gain on every winner if at some point you are guaranteed to lose the entire stake. Does it matter that you were up 1,000% beforehand? Risk-taking has a well-developed mathematics behind it, but plain common sense already gets you a long way — and plenty of titans still fail right here.
The thing I miss most in this group is the ability to think in systems. Many believe that if you bolt together a few well-known rules into a strategy, it simply has to work. Maybe check whether it actually does? The reality is that there are no absolute truths. There is no sacred stop-loss. Which stop, for which pattern? One setup wants a 7% price stop; another wants a three-day time stop. Never catch a falling knife, goes another treasured line — and I can build you a system that catches falling knives all day long and turns a profit. Dividend investing? No such thing exists. There are stock-selection algorithms; one of them will end up holding more dividend payers, another fewer.
On markets there are no rules, only systems. Miss that and you’ll walk into trap after trap. Too many parameters? Wonderful, sellable past results and dismal future ones. Carve the rules on a stone tablet and worship them? It won’t be enough. A system has to be tended, monitored continuously: how robust is it, how does it react when the environment or the parameters shift?
And that same way of seeing helps beyond strategy design. To my mind trading is, at bottom, an information-management problem. At every moment you have to decide what to ignore out of an infinite stream, and what to weigh — and, on top of that, hold a set of mutually contradictory pieces of information at once. A good information-management system is a heavy, dependable support, both while you’re learning and while you’re trading, in an environment that never stops changing.
I won’t keep listing the factors that decide the road to success. In this respect trading is a bit like marriage. They say four or five things have to be right for a lasting one — and the catch is that if any single one is missing, that alone can run the whole thing aground. I suspect a successful trading career works the same way. There are a few factors, none of them demanding superhuman gifts, but you need all of them lined up at once.
When they do line up, a very small fraction of the young titans turn into rich, successful traders, and the great majority get the bitter pill: a retreat from a field they’ve already sunk enormous work into. A hard, unpleasant decision — though still a better one than letting the market make it for you.
That’s the list of investor types as I’ve come to recognize them. I hope sketching out the possible life-paths gives everyone a moment of reflection, and a way to decide for themselves what role they want this whole business to play in their life.
